
Roth conversions · 2026 rules
Pay the tax now, or pay it later? Run your numbers.
A Roth conversion moves money from a traditional IRA or old 401(k) into a Roth IRA. You pay income tax on what you convert this year, and qualified withdrawals later can be tax-free. Whether that’s smart depends on your tax rate today versus the one you expect in retirement. The calculator below shows you the difference in about a minute.
What is a Roth conversion?
Most retirement savings sit in traditional, pre-tax accounts: 401(k)s, 403(b)s and traditional IRAs. You got a tax break when the money went in, but every dollar that comes out in retirement is taxed as ordinary income. A Roth conversion flips that. You move some or all of that money into a Roth IRA, pay the income tax on the converted amount now, and from then on the money can grow tax-free. Once you’re 59½ and the Roth has been open at least five years, withdrawals are generally tax-free, and a Roth IRA has no required minimum distributions during your lifetime.
In short: a Roth conversion is a bet that your tax rate later will be the same or higher than it is today. If it will be, converting can put more money in your pocket. If it won’t, it usually doesn’t make sense. That’s why the numbers matter more than the sales pitch.
Roth conversion calculator
Your account
How much is in your traditional IRA or old 401(k), and how much would you convert?
Your taxes
Your federal tax bracket now, and your best guess for retirement.
Your timeline
How long until you’ll start using this money, and what it might earn.
Your results
Hypothetical illustration using the same growth rate for every account and federal tax only. It does not include state tax, the pro-rata rule, Medicare IRMAA surcharges, taxation of Social Security, deductions, or future tax-law changes. Not tax advice. Review any conversion with a qualified tax professional before acting.
When a Roth conversion can make sense
Your tax bracket is lower now than it will be later
Early retirement years, a gap before Social Security starts, or a lower-income year can be a window to convert at a lower rate.
You want to shrink future RMDs
Required minimum distributions from traditional accounts start at age 73 (75 for people born in 1960 or later). Converting earlier can reduce those forced, taxable withdrawals.
You want a tax-free bucket
Having money in taxable, tax-deferred and tax-free buckets gives you choices each year about which dollars to spend. That’s tax diversification.
You want to leave tax-free money to family
Heirs generally must empty an inherited IRA within 10 years. Inherited Roth money can come out income-tax-free; inherited traditional money is taxed to them, often in their peak-earning years.
The risks and rules to know first
- The tax bill is real and immediate. Every converted dollar is added to this year’s taxable income, and it can push you into a higher bracket.
- You can’t undo it. Since 2018, a Roth conversion can’t be reversed (recharacterized).
- The five-year rules. Each conversion has its own five-year clock. Withdraw converted money before 59½ and within five years and a 10% penalty can apply.
- Medicare premiums. Medicare looks back two years at your income. A large conversion at 63 or later can raise your Part B and D premiums (IRMAA).
- Social Security taxation. Extra income in a conversion year can make more of your Social Security benefit taxable.
- Paying the tax from the IRA weakens the math. Using outside savings to pay the tax usually works out better, and under 59½ money withheld from the IRA may be penalized.
- Deadline. Conversions count in the calendar year they happen. There’s no April extension like with contributions.
Roth conversion vs. “backdoor Roth”
They’re related but not the same. A Roth conversion moves existing pre-tax retirement money into a Roth and has no income limit. A backdoor Roth is a strategy for high earners who are over the income limit for direct Roth contributions: they make a non-deductible IRA contribution and then convert it. The pro-rata rule matters here. If you have other pre-tax IRA money, part of every conversion is taxable, so the backdoor isn’t as simple as it sounds.
| Traditional IRA / 401(k) | Roth IRA | Properly structured IUL | |
|---|---|---|---|
| Money going in | Pre-tax (deductible) | After-tax | After-tax |
| Growth | Tax-deferred | Tax-free if qualified | Tax-deferred |
| Money coming out | Taxed as income | Tax-free if qualified | Can be accessed tax-free through policy loans if managed properly |
| Contribution limits | Yes | Yes, plus income limits | Based on IRS life insurance rules, not income |
| Required distributions | Yes, from 73 | None for the owner | None |
| Market losses | Yes | Yes | 0% floor on index credits |
| Life insurance for family | No | No | Yes, generally income-tax-free |
Where life insurance fits in a tax-free retirement plan
A Roth conversion is one way to build a tax-free bucket. It isn’t the only one, and it doesn’t protect your family. That’s where life insurance comes in, and it’s the part of the plan most people forget.
- Protect the plan while it’s working. If you pay a large conversion tax now, your family is counting on those dollars to grow for years. Life insurance with living benefits protects them if you die early, and can let you access part of the benefit if you have a serious illness.
- A second tax-free bucket with no income limits. A properly structured IUL grows tax-deferred, has a 0% floor on index credits, and can provide tax-free access through policy loans when it’s funded and managed correctly. Read Is IUL tax-free? for the fine print.
- Protect the money from market drops first. If you’re close to retirement, moving an old 401(k) into a fixed indexed annuity can protect principal and create lifetime income, while a partial Roth conversion handles the tax side.
More on the bigger picture: What is an IUL and how does it work? and 5 retirement planning moves to make before you retire.
Free: The Tax-Free Retirement & Protection Guide
My 10-page guide to income, taxes, Roth conversions, principal protection, Social Security, life insurance and legacy, with the checklist I use with clients.
Your guide is opening in a new tab. Next, grab a time for your free call. Taking you there now…
Why I care about this
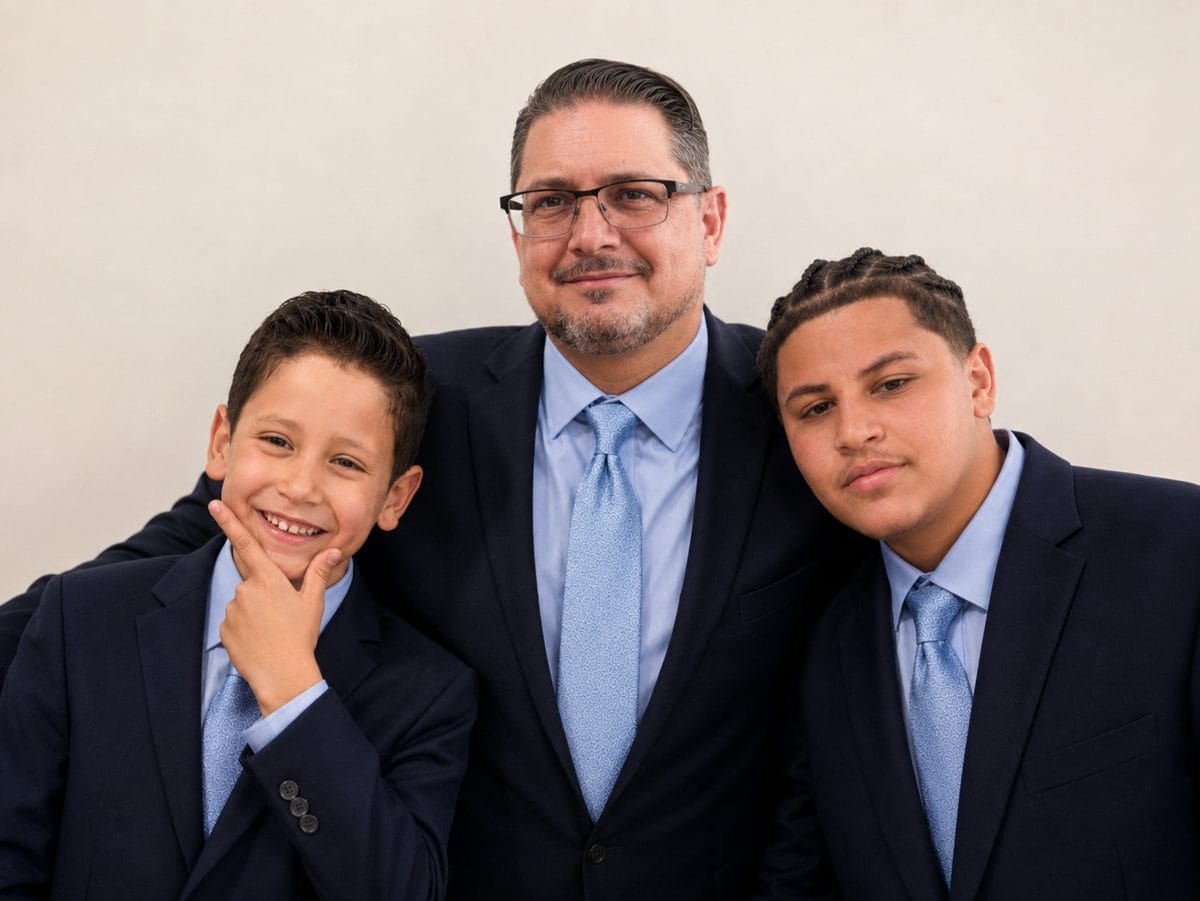
I’m Cory Levine, a licensed insurance professional, a widower and a dad of two boys. When my wife became seriously ill, we spent down much of our retirement savings trying to keep her comfortable. That taught me that a retirement plan isn’t just about taxes and returns. It has to hold up when life doesn’t go to plan.
I’m independent, so I’m not tied to one company. I’ll run your real numbers, show you when a Roth conversion helps and when it doesn’t, and tell you plainly if what you have is already working. I’m based in Boca Raton and work with clients nationwide by phone and video.
Roth conversion FAQs
How much tax will I pay on a Roth conversion?
The converted amount is added to your taxable income for the year and taxed at your ordinary income-tax rates. Converting in pieces over several years can keep you in a lower bracket.
Is there an income limit for Roth conversions?
No. Anyone can convert any amount. Income limits apply to direct Roth IRA contributions, not conversions.
Can I undo a Roth conversion?
No. Recharacterizing (reversing) a conversion hasn’t been allowed since 2018.
What is the five-year rule for Roth conversions?
Each conversion has its own five-year clock. If you’re under 59½ and withdraw converted money before five years, a 10% penalty can apply. Earnings are tax-free once you’re 59½ and your first Roth has been open five years.
Should I convert my whole IRA at once?
Usually not. Many people convert a portion each year to “fill up” a lower bracket without jumping into a higher one. The right amount depends on your income, age, Medicare timing and goals.
Is a Roth conversion better than an IUL?
They do different jobs. A Roth conversion moves existing retirement money into a tax-free account. A properly structured IUL builds a separate tax-advantaged bucket and adds life insurance and living benefits. Many plans use both.
Want to know if a Roth conversion makes sense for you?
Bring your latest tax return and account statements. In a free 15-minute call I’ll show you how much to convert, if any, and how it fits with the rest of your plan. No pressure.
This page is general education, not tax, legal or investment advice. Roth conversions are taxable and irreversible; tax rules can change. Consult a qualified tax professional before converting. Insurance and annuity guarantees depend on the claims-paying ability of the issuing company. Policy loans and withdrawals reduce cash value and death benefit and can cause a policy to lapse. Cory Levine is a licensed insurance professional and does not provide tax or legal advice.




