Term life insurance you can actually use while you're alive
Most policies only pay out after you're gone. But modern term life with living benefits can be designed to help you access a portion of your coverage if you're diagnosed with a serious illness — when your family needs it most.
- Term life covers you for a set number of years (10, 20 or 30) for the lowest cost per dollar of coverage.
- Most families need about 10–15 times their yearly income, plus the mortgage and big goals like college.
- Many term policies can include living benefits, so you may be able to use part of your coverage if you’re seriously ill.
- The death benefit is generally income-tax-free to your family.
Traditional life insurance protects your family after you die. But what about while you’re alive — and you get sick?
A serious diagnosis — cancer, a heart attack, a stroke — doesn't just threaten your life. It also threatens your income, your savings, and your family's stability at the exact moment the bills pile up. Old-school term life does nothing until the funeral. That’s why having life insurance with living benefits can make a real difference. It can help you handle the bills while you focus on getting better.
Here’s the part most people never hear: with the right policy design, a critical illness (like a heart attack, stroke, or cancer), a chronic illness, or a terminal diagnosis can let you access part of your own death benefit early — while you’re still alive to use it. Same premium. You’re covered when it counts — not just after you’re gone.
One policy. Protection at all four of life’s hardest moments.
If you’re diagnosed with a qualifying critical, chronic, or terminal illness, you can choose to access a portion of your death benefit early, while you’re living. The amount you access is subtracted from your death benefit, and the rest still goes to your family. Because it’s paid early, the check you receive is typically less than the amount you access. Eligibility, limits, and costs depend on the policy, your health rating, and your state.
Availability, amounts, and triggers vary by carrier, product, and state. This is educational only — your real illustration shows exactly what your policy can be designed to do.
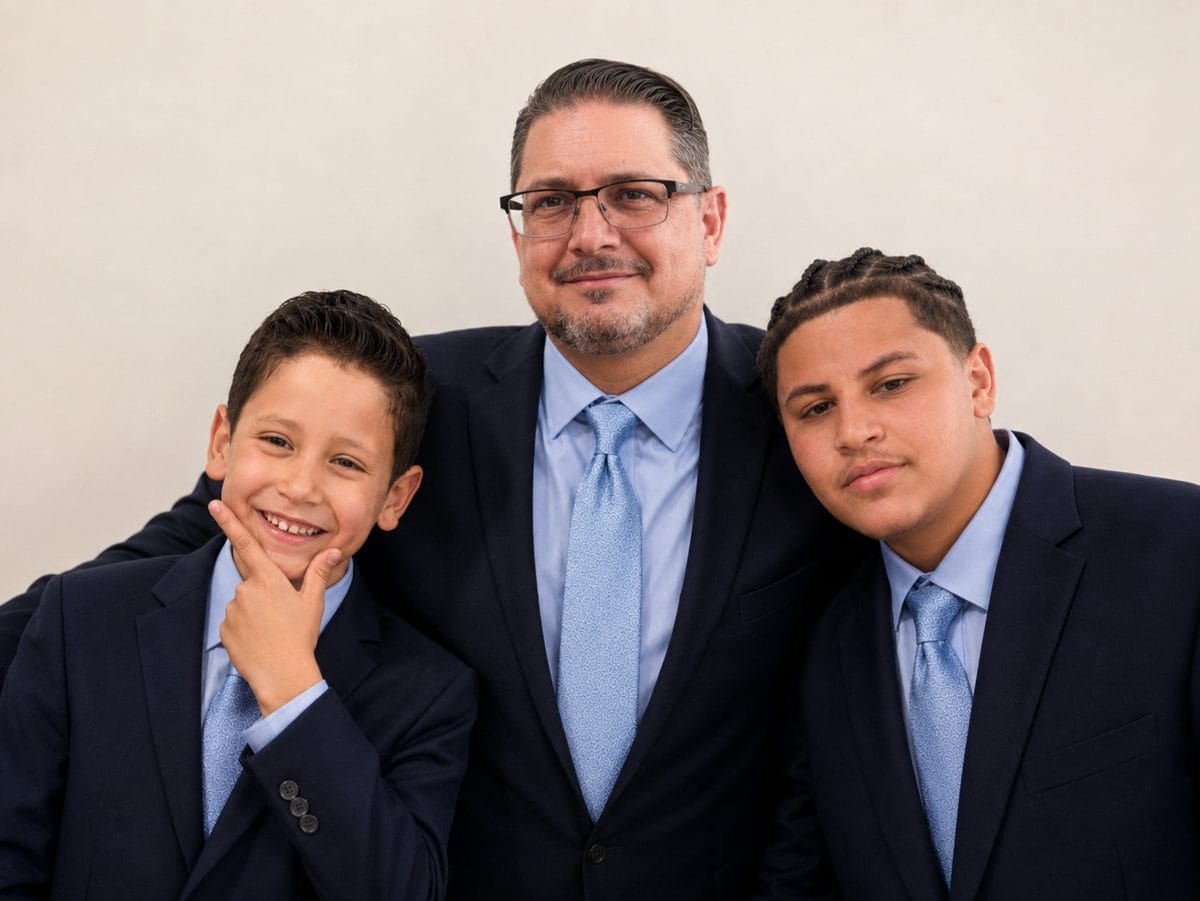 Cory and his boys — Boca Raton, FL
I've lived the moment this protects against.
I’m a licensed insurance professional — and a widower. During the birth of our first son, my wife was suffering from a cognitive impairment. If we’d had living benefits then, it would have changed our lives. I lost her, and I’ve raised our two boys on my own ever since.
So when I sit with a family and talk about protecting each other, it isn’t a script. It’s what I’ve lived.
My job is simply to explain it in plain English, run your real numbers, and tell you honestly when what you already have is enough. No pressure — ever.
📅 Book a Call with CorySame idea. Very different protection.
Traditional term life
- Pays out only after you pass away
- No help during a serious illness
- Coverage often ends when the term expires
- Nothing to access while you're alive
Term with living benefits
- Access part of your benefit if seriously ill
- Cash when treatment and bills hit hardest
- Options to keep coverage for life
- Protection you can actually use while living
Real families. Real relief.
"Knowing that you are also a widower helped me know you understood our needs… Now if I get sick I will get my life insurance while I'm alive."
"He made this complex product easy to understand. We chose what worked best for us."
How term life insurance works
You pick a coverage amount and a length of time — the “term.” You pay a set premium, usually monthly. If you pass away during the term, your family receives the death benefit. If you outlive the term, the coverage simply ends.
That’s why term is the most affordable way to protect your family during the years they depend on your paycheck: while the kids are young, while you’re paying off the house, and while you’re building savings.
With living benefits, a term policy can also work for you while you’re alive. Here’s how living benefits work, from someone who’s lived it.
How much life insurance do I need?
A simple rule of thumb is 10 to 15 times your yearly income. A better answer adds up what your family would actually need: income for the years they depend on you, the mortgage, other debts, college, and final expenses — minus the coverage and savings you already have. Try it with your own numbers:
How long should your term be?
Match the term to the years your family depends on you. Most people choose the term that runs until their youngest child is on their own or their mortgage is paid off.
| Term length | Often a good fit if… |
|---|---|
| 10 years | You need coverage for a short gap, like a business loan or the last years before retirement. |
| 20 years | You have young children or a newer mortgage. This is the most popular choice. |
| 30 years | You just bought a home or had a baby and want the longest protection at a locked-in price. |
Living benefits, answered plainly.
Do living benefits cost extra?
On many modern term policies, living benefit riders are included at little or no additional cost. For example, your illustration shows which riders are included and whether they cost extra. And there's no charge to find out.Who qualifies for this kind of coverage?
Most healthy adults can qualify, and options exist across a wide range of ages and health situations. The only way to know your real rate is a quick, no-pressure conversation — no exam required to get started.Is this the same as long-term care insurance?
Not exactly — but for many families it fills a similar gap. Chronic-illness living benefits can help pay for care while keeping the death benefit for your family. We'll walk through the differences on your call.What if I already have a policy?
Bring it. I'll review what you have honestly — and if it's already doing the job, I'll tell you to keep it. And if there's a gap, I'll explain it clearly.What happens when my term life policy ends?
Coverage stops and you stop paying. Many policies let you convert to permanent coverage before the term ends, without a new medical exam.Can I get term life insurance without a medical exam?
Often, yes. Depending on your age, health and the amount of coverage, many people qualify with just a health questionnaire.Can I have more than one life insurance policy?
Yes. Many people keep coverage through work and add a personal term policy, because work coverage usually ends when you leave the job.How much does term life insurance cost per month?
It depends on your age, health and how much coverage you want. Term is the most affordable type of life insurance, and locking in while you’re young and healthy keeps it that way.Real example rates
What does term life insurance cost?
Monthly premiums for a man, level for the full term. Pick an age and coverage amount.
| Term | Preferred Plusbest health | Preferredvery good health | Standardnon-tobacco | Preferredtobacco | Standardtobacco |
|---|
Example monthly rates for a male, taken from carrier illustrations dated September 2026. Premiums stay level for the initial 10, 15, 20, or 30 years, then increase each year. Living benefits for qualifying terminal, chronic, and critical illness are included at no extra premium on these example policies (a fee applies if used). Not an offer or contract; coverage is subject to underwriting, and your rate depends on age, gender, health, tobacco use, coverage amount, and state.
Term vs. whole life vs. IUL
| Term life | Whole life | IUL | |
|---|---|---|---|
| How long it lasts | 10–30 years | Your whole life | Your whole life |
| Cost | Lowest | Highest | In between, flexible |
| Cash value | None | Fixed, guaranteed growth | Growth linked to a market index, with a 0% floor |
| Best for | Protecting your family during the working years | Lifetime coverage with guarantees | Lifetime coverage plus tax-advantaged retirement income |
Want the full comparison? Read Whole Life vs. IUL vs. Term: Which One Fits You? or see how an indexed universal life (IUL) policy works.
Is term life insurance taxable?
In most cases, no. The death benefit your beneficiaries receive is generally not counted as taxable income (IRS). There are exceptions, like interest paid on the benefit or policies that were sold or transferred, so it’s worth a quick check for your situation.
Pros and cons of term life insurance
| Pros | Cons |
|---|---|
| Lowest cost for the most coverage Premium locked in for the whole term Simple and easy to understand Can include living benefits Many policies can convert to permanent coverage later | Coverage ends when the term ends No cash value Renewing after the term is much more expensive |
Who needs term life insurance?
- Parents with children who depend on their income — see life insurance for single parents
- Homeowners who want their family to keep the house
- Couples where one income would be hard to lose
- Business owners with loans or partners to protect
See what your family's protection can actually do.
Your real numbers. Honest answers — including "keep what you have" when that's the truth. Pick a time below.